Loading

Longer references — doing business in Egypt, the annual tax calendar — as downloadable PDFs.
When must an Egyptian parent prepare consolidated statements, and who is in them? EAS 42 ties consolidation to control; the Companies Law regulations and listing rules add duties.
Why does the book balance differ from the bank statement? The rules on books do not name the reconciliation, but the Commerce Law requires books that show the financial position.
At what rate is a foreign-currency transaction recorded, and where does the exchange difference go? EAS 13 as replaced in 2024, the lapsed appendix periods and the tax position.
Where and in what language must a foreign group's Egyptian entity keep its books? What the commerce and tax procedure laws say on place and language, and producing the books.
Which texts govern transfer pricing in Egypt today? Article 30 of the Income Tax Law, Articles 38 to 40 of its regulations as amended in 2018, and the 2023 related-person test.
Who must issue Egypt's electronic receipt? A registered seller to final consumers, once a decision covers it. All scheduled dates have passed; receipts are due within 24 hours.
Serving clients or platforms abroad from Egypt is taxable in Egypt; exported services are zero-rated for VAT given a contract, an invoice and a bank transfer.
Are founders' shares locked up? How does an Egyptian company give staff shares or options? The rules, the shareholders' agreement and the tax on granted shares.
Do Egypt's freelancers and content creators need to register for tax? Yes, once they start; income is taxed on net profit, or on turnover under the simplified regime.
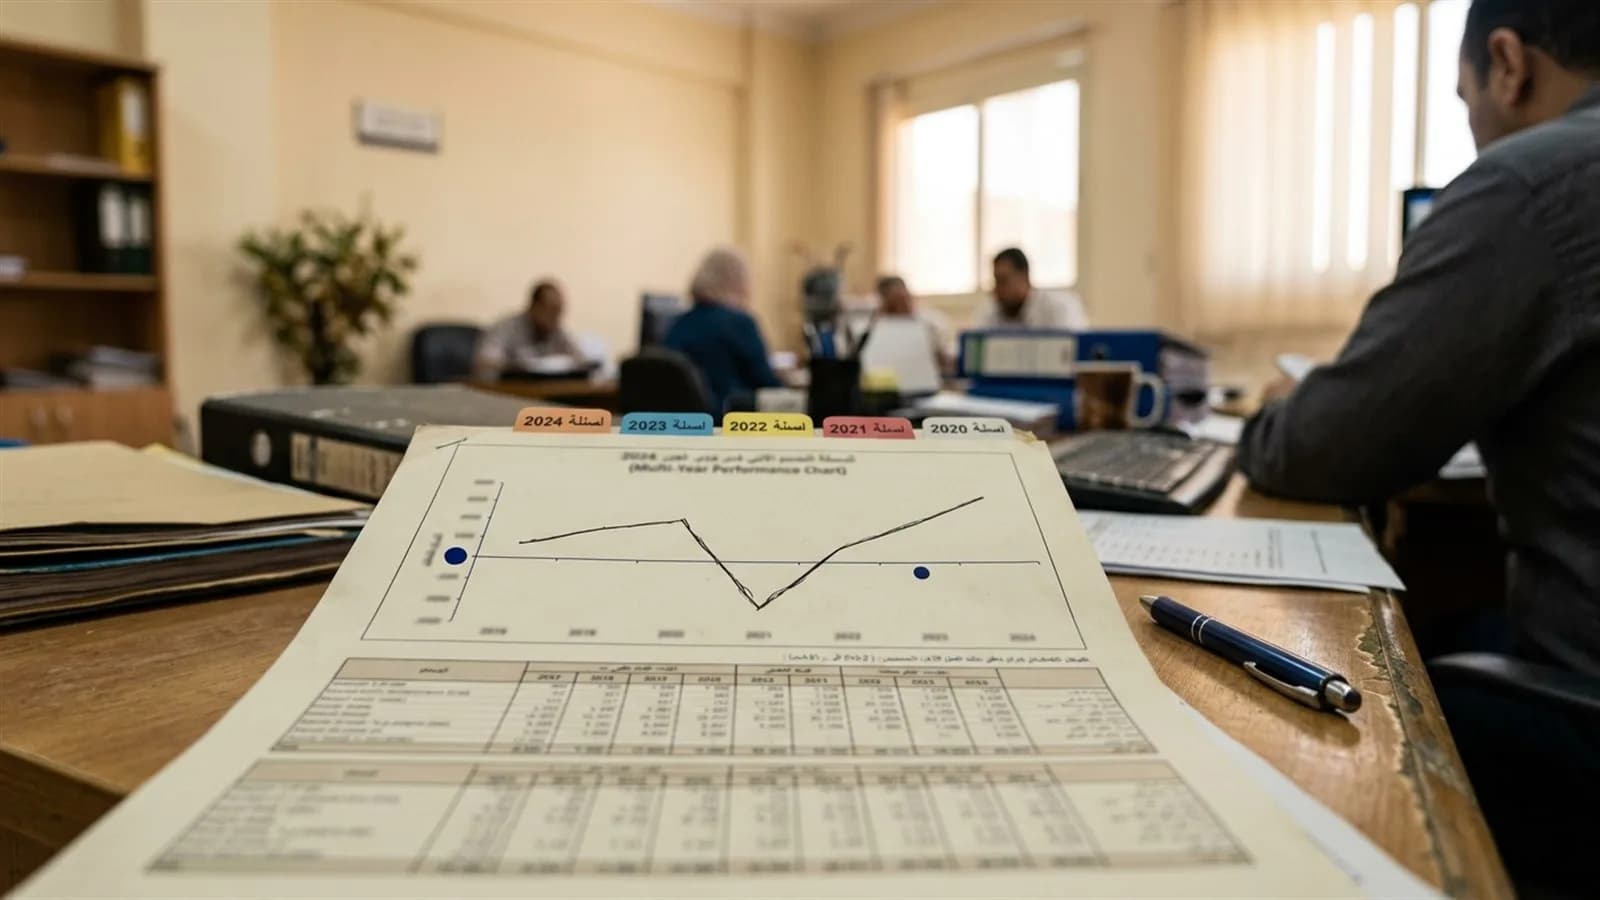
How many years can a tax loss be carried forward in Egypt? Five, used in strict order, never renewed, with separate rules for long-term contracts and several income sources.
What should an Egyptian company prepare before an investor comes in? Audited accounts, sound books, clean tax and insurance files, and a properly run capital increase.
Why does tax depreciation differ from the accounting charge? Fixed rates on cost or on a declining pooled base, and an elective 30% first-year allowance, create deferred tax.